Macro VAR
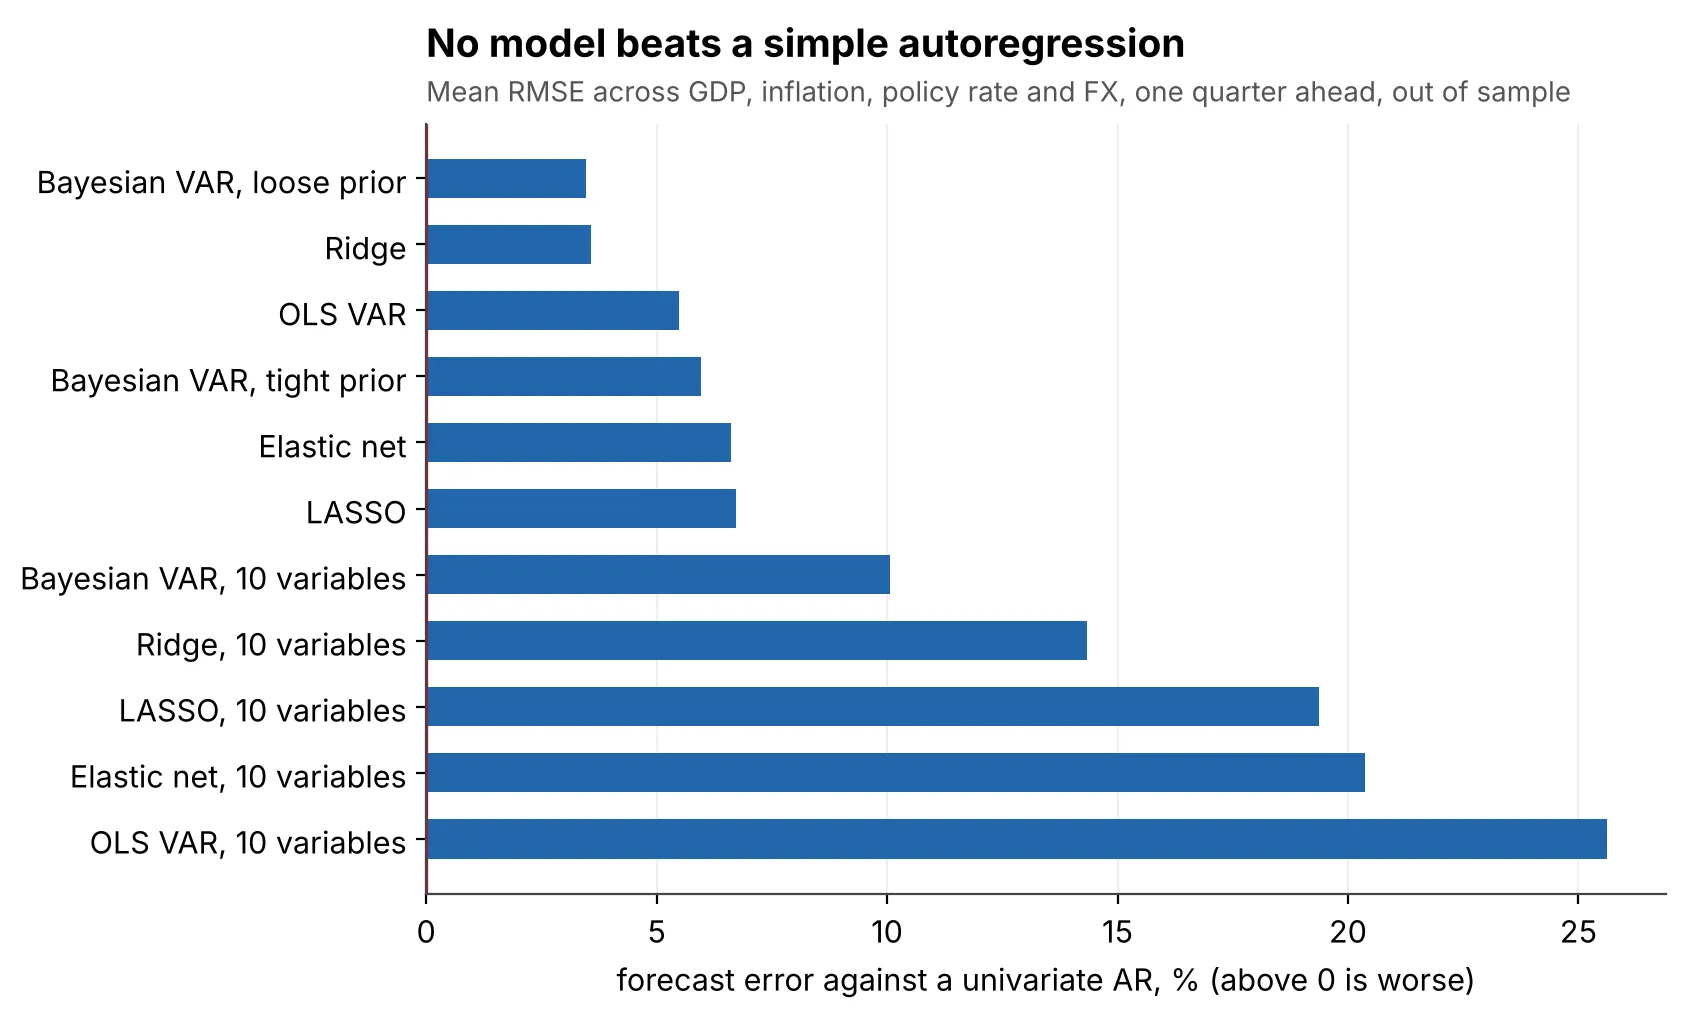
After 1,000+ models, nothing reliably beats a simple autoregression.
capability: Macro / econometrics
category: Econometrics
date: July 2026
question
What actually forecasts US growth, inflation and rates once the models can't peek at the future? One study in three stages.
methodology
- Stage 1: which variables and which estimator.
- Stage 2: whether adding economic shocks helps.
- Stage 3: the same idea across 1,014 models, using data as it was first published.
result
- No model family beats a simple autoregression.
- A standard filter quietly uses future data, by two-thirds of the cycle's own size.
- The best shock models look 12% better, but that's no more than luck would give.
figures
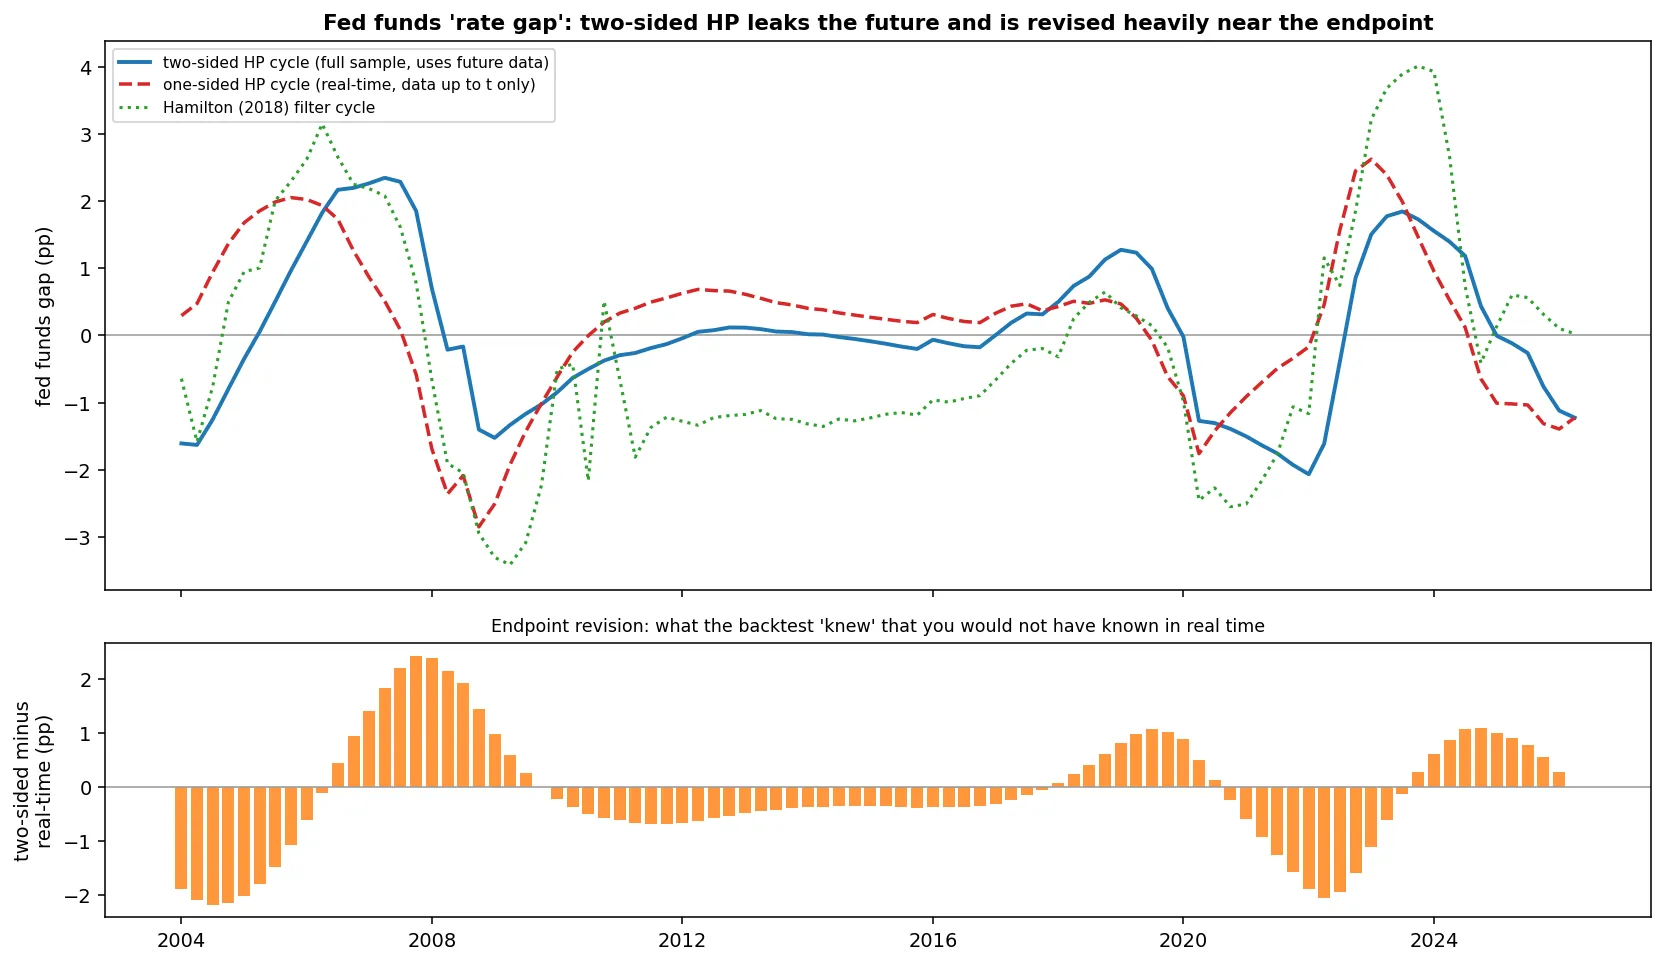
Figure 1. The two-sided HP filter knows the future near the endpoint; a real-time filter does not.
caveats
- About 30 years of quarterly data, so every test has limited power.
stack
Pythonstatsmodelsscikit-learnarchFREDALFRED