Hi, I'm Nicholas 👋
Quant researcher & engineer | Data, markets & code
I design and test systematic trading strategies — Always refining, always iterating.
featured research
projects across systematic equities, volatility, rates, macro econometrics, machine learning and market-making systems. methodology, result, caveats, code and writeup.
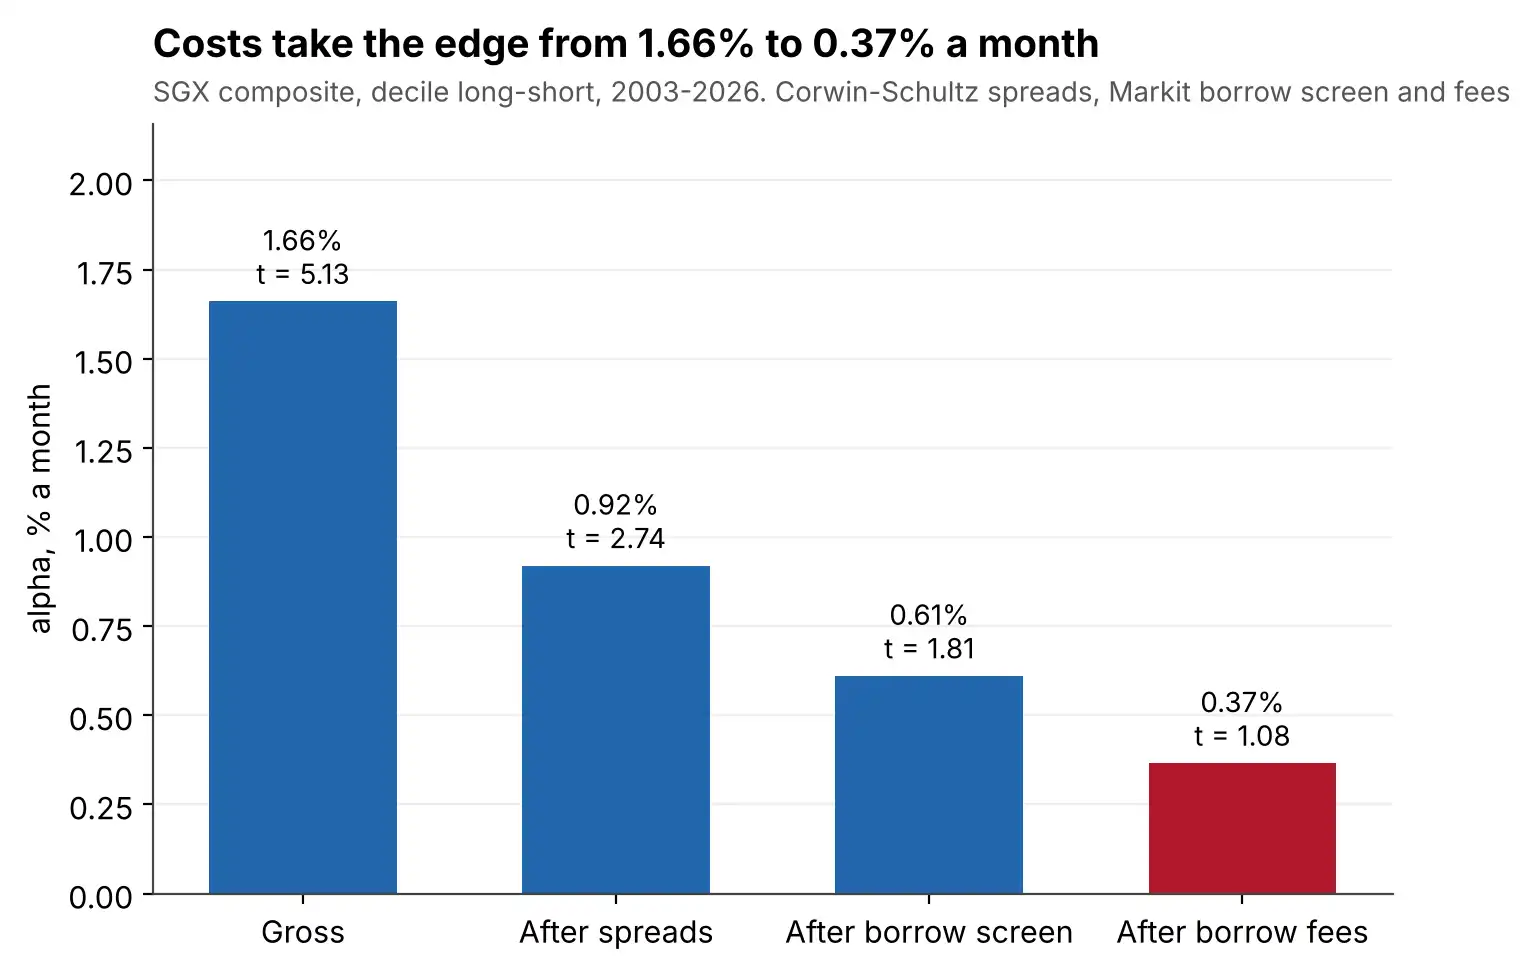
Multi-Factor Equities on SGX
Classic stock-picking factors work in Singapore. Trading costs take almost all of it.
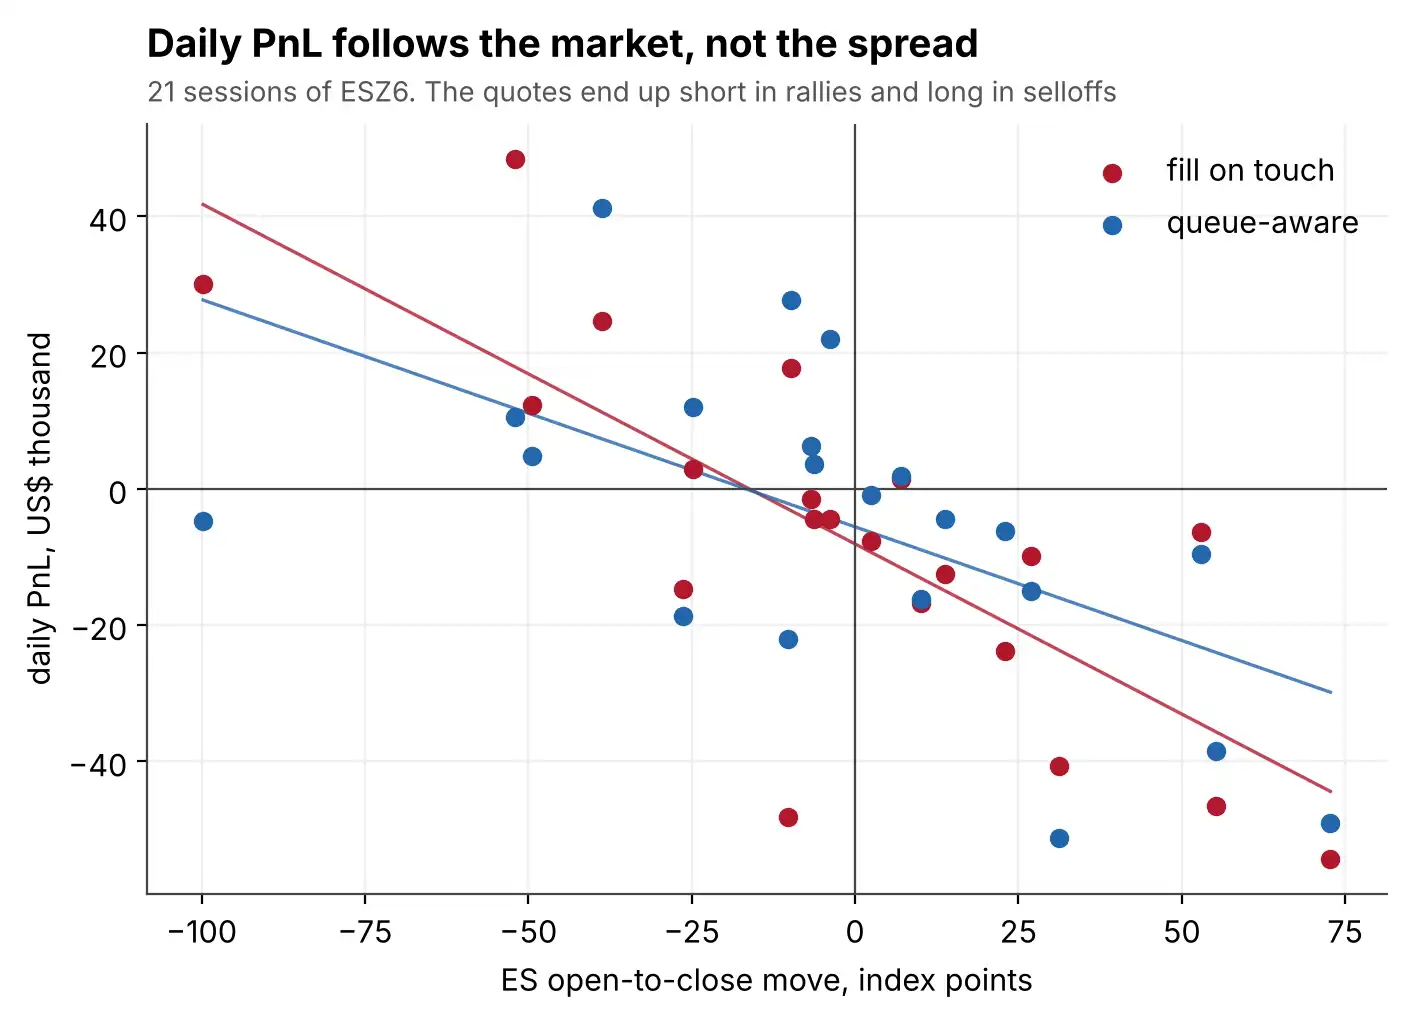
Market Making
A C++ market maker tested on 21 days of S&P 500 futures. It loses money, and the market's direction explains most of why.
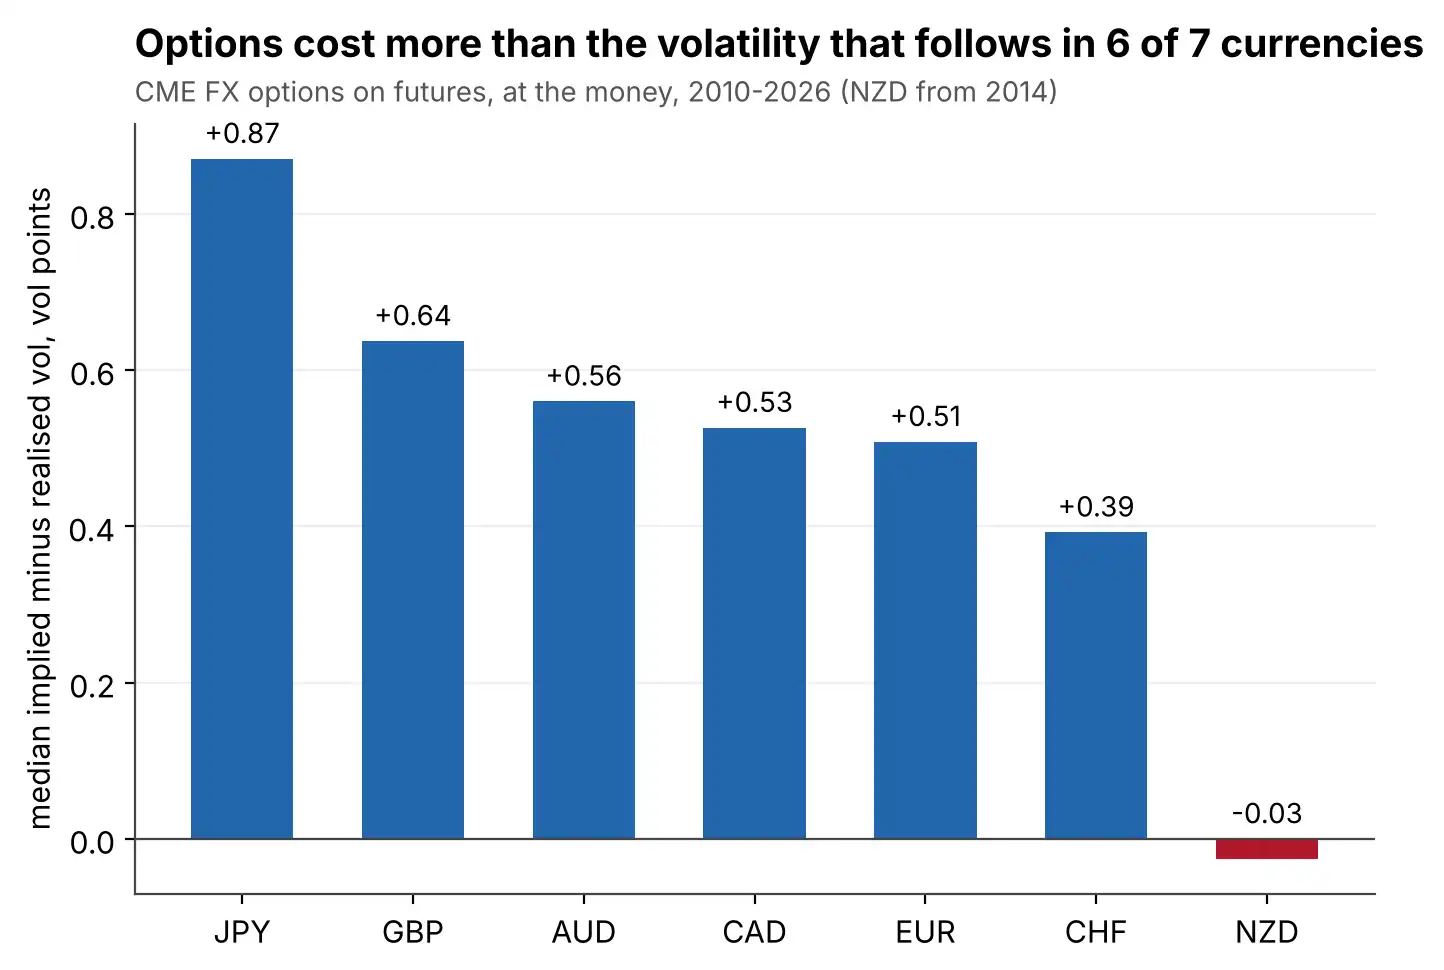
FX Options VRP
Sixteen years of CME currency options. They cost more than the volatility that follows, like insurance.
Treasury Futures
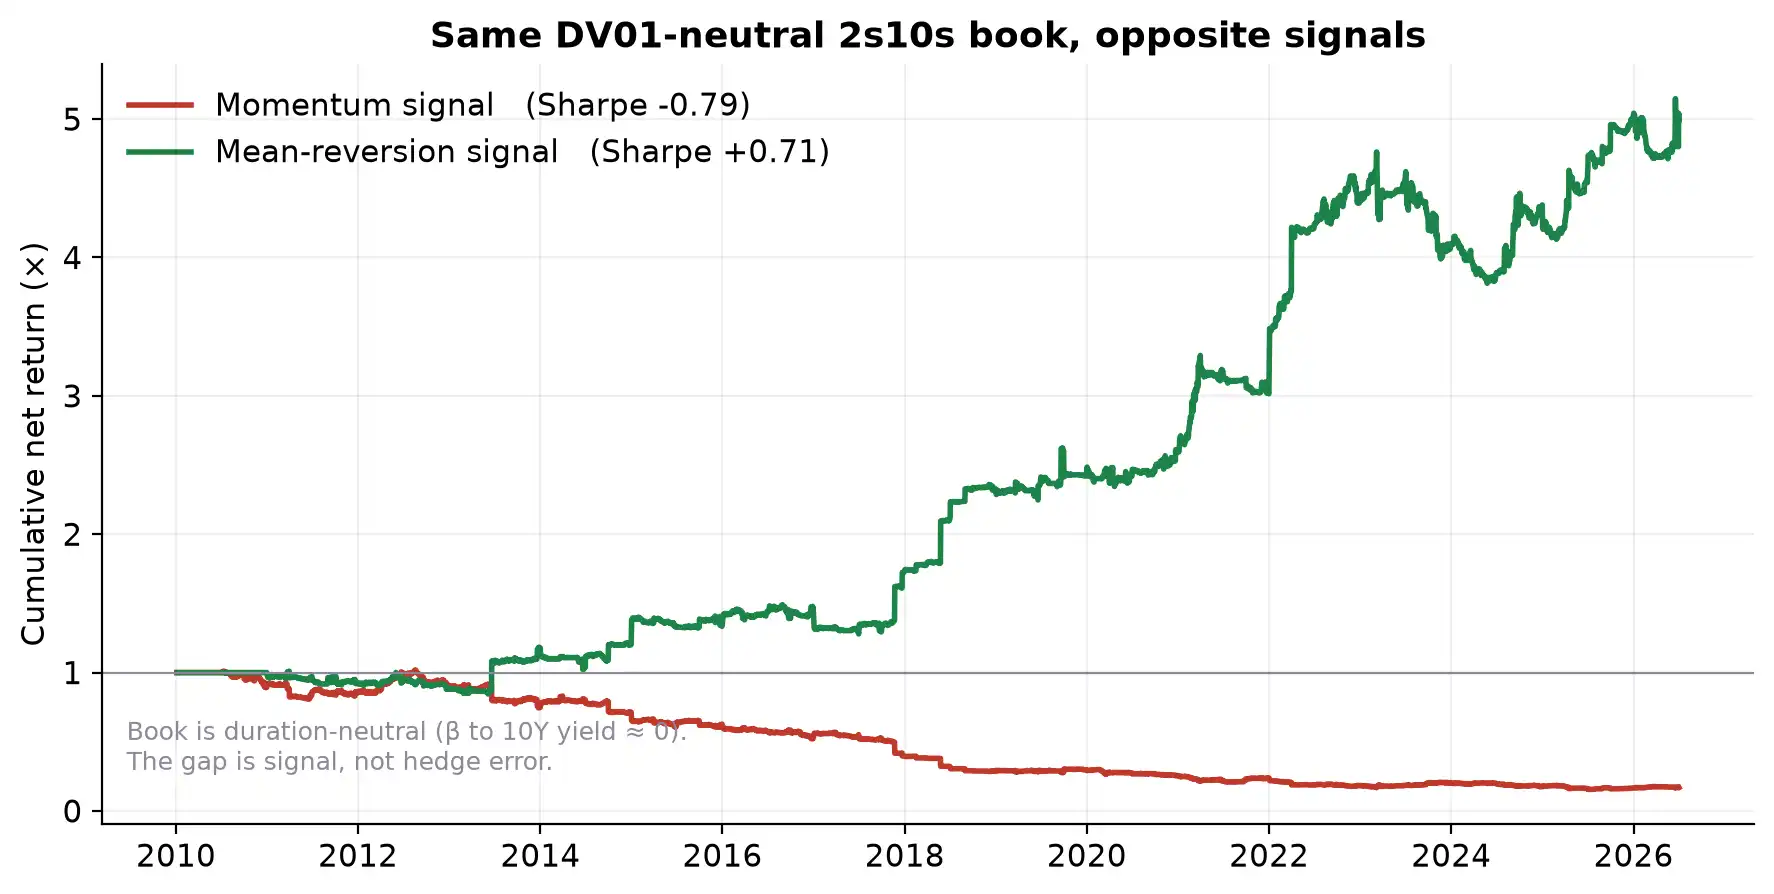
Same hedged Treasury curve trade, two signals: it makes money betting on reversal and loses betting on trend.
LSTM
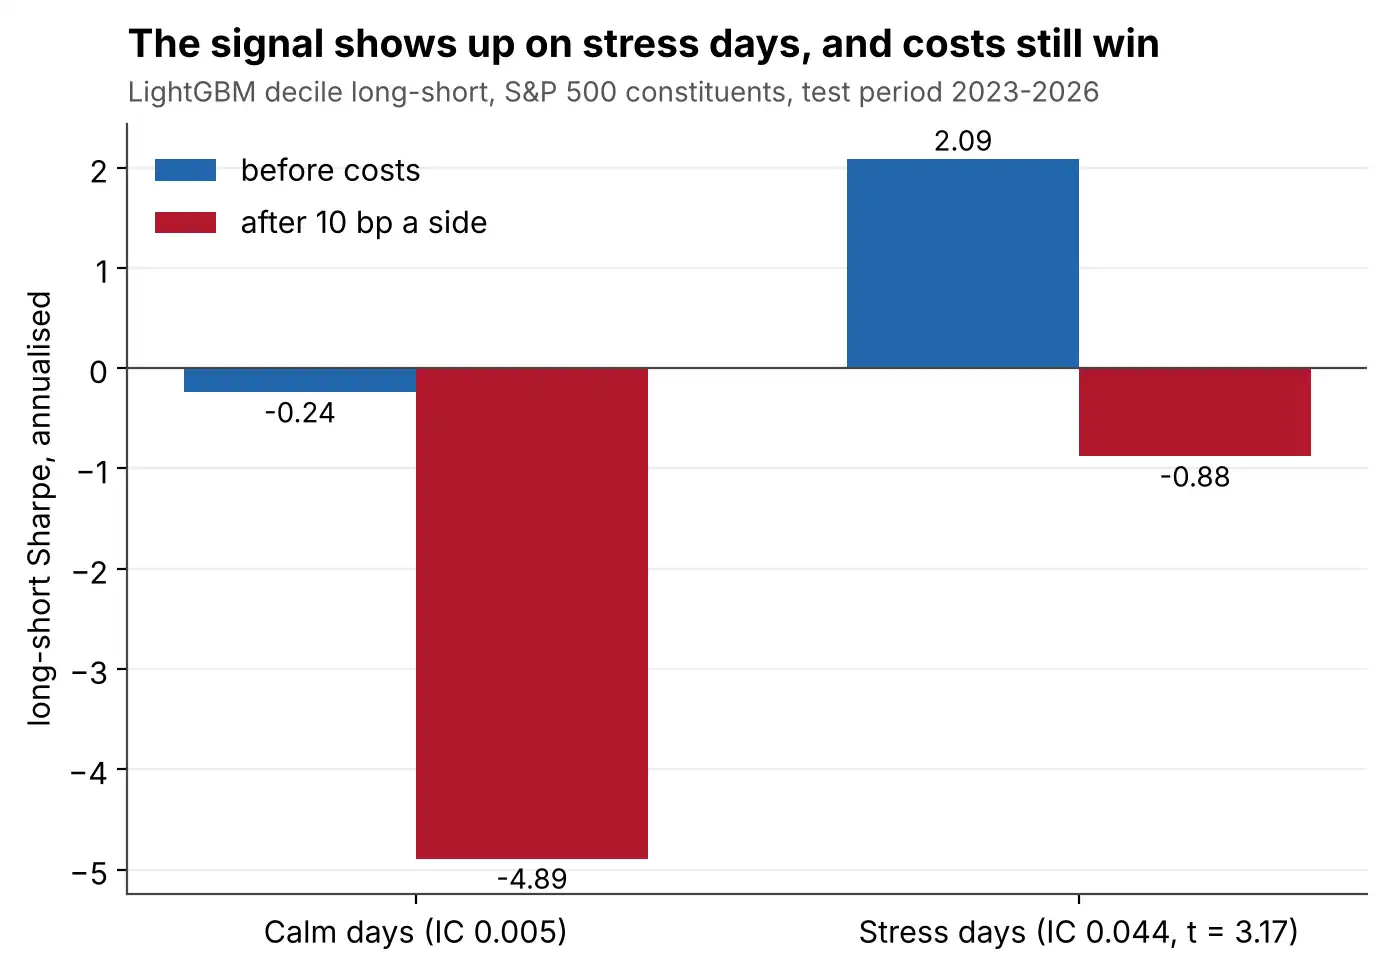
An LSTM against eleven simpler models on 518 S&P 500 stocks. None beats guessing zero.
Macro VAR
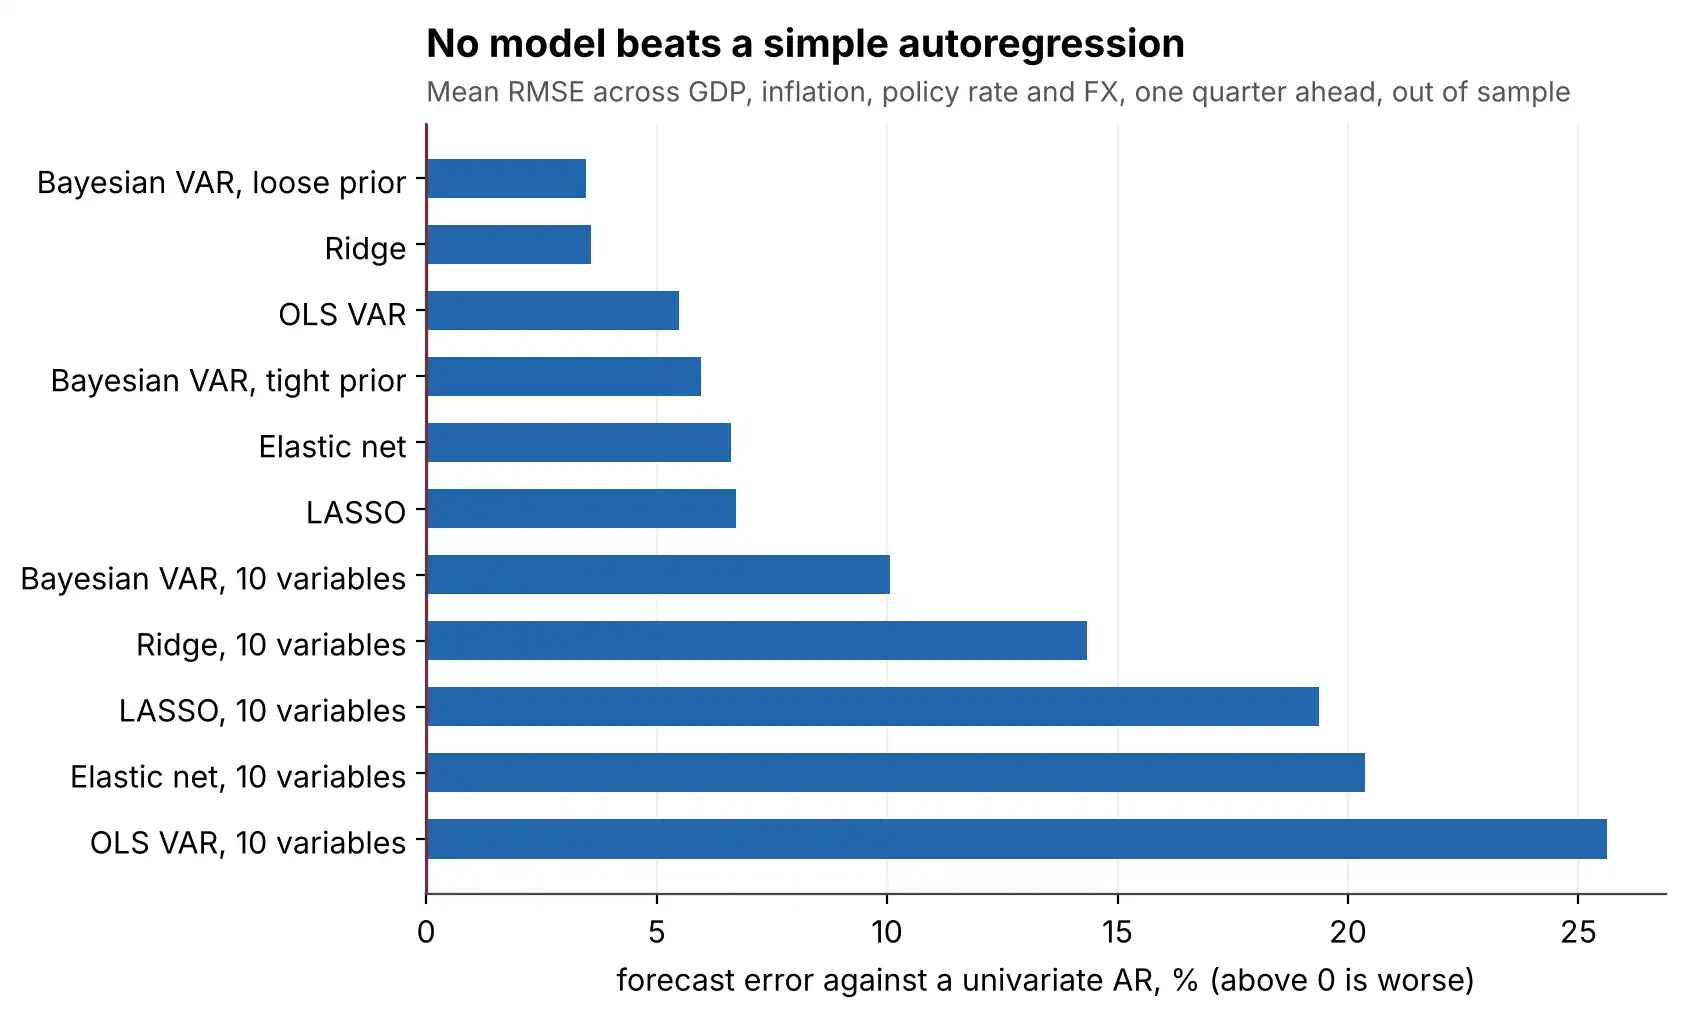
Over 1,000 models to forecast US growth and inflation. None reliably beats the simplest one.